You invest
You buy shares in the company that owns the house. You have a stake in the asset, not a right of use or a club membership.
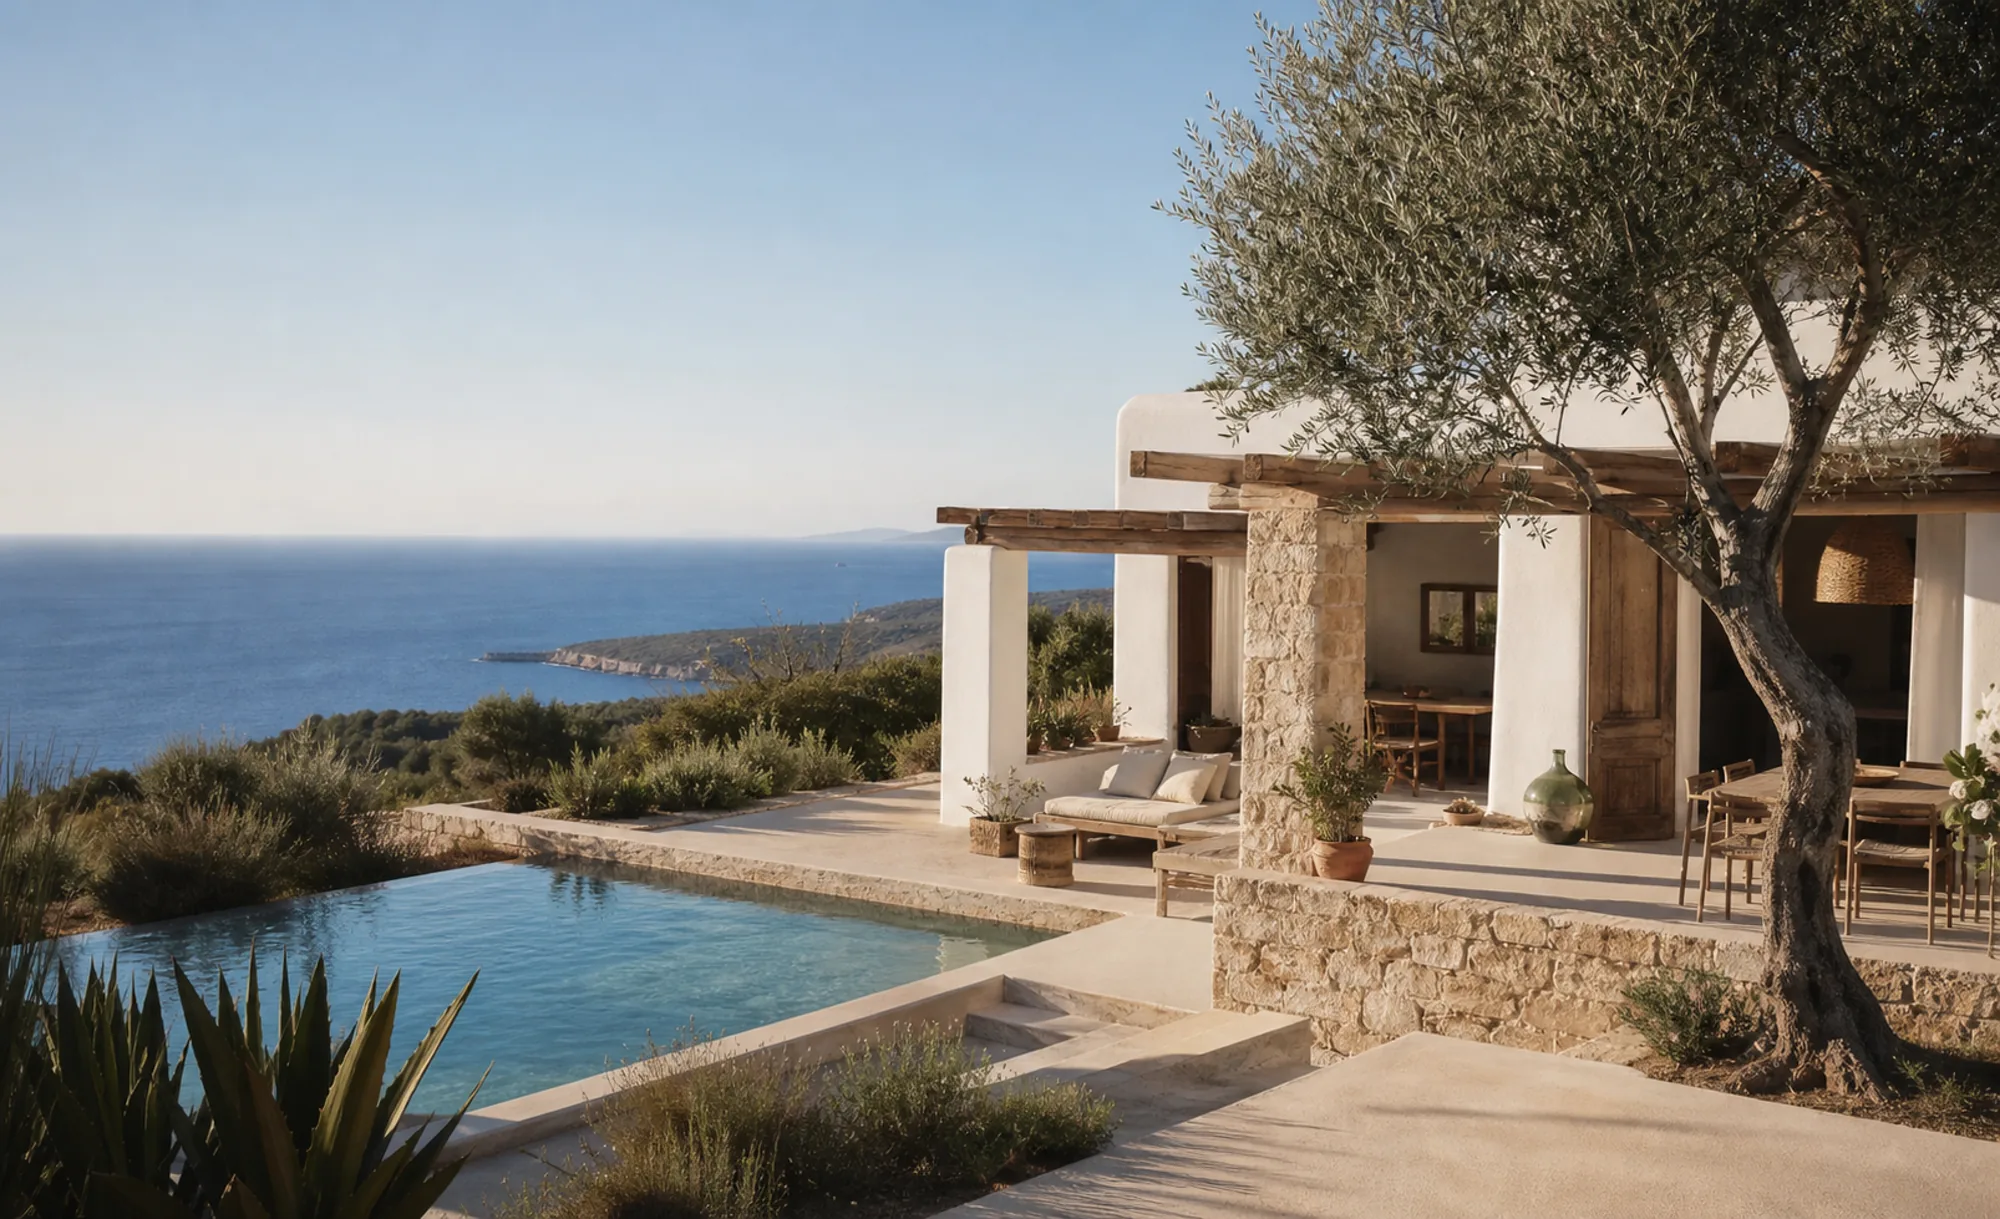
Six families. One house. Fully managed.
From €40,000, you can acquire shares in the company that owns a Mediterranean home with a pool. The model provides for three weeks of use a year, at a co-owner rate of €675 per week in the mid or low season, compared with an estimated guest value of €1,800. At other times, the home is marketed for holiday rental. In the simulated central scenario, income would cover the forecast costs and produce an annual payout; neither outcome is guaranteed. We handle the purchase, rental operations and maintenance.
Your week at the house: €675. A guest's week: €1,800.
PROPIA is at an early stage and no opportunity is currently open. The figures are simulated; the information sets out the assumptions and principal risks.
CASA RIU / SIMULATED EXAMPLE
A house where the kids already know where everything is. The table outside, a swim before dinner, the same friends next year. None of that shows up in a spreadsheet, and it is half the reason to do this.
You buy shares in the company that owns the house. You have a stake in the asset, not a right of use or a club membership.
We market and maintain it and report to you. Any net income available for distribution is allocated according to each shareholder’s interest.
In the mid or low season, a week with an estimated guest value of €1,800 has a co-owner rate of €675, deducted from the annual payout.
THE COMPARISON NOBODY MAKES FOR YOU
Almost nobody compares PROPIA with an index fund, because almost nobody puts €60,000 into a fund in order not to go on holiday. What you're really deciding is this: the same money, the same summer weeks, three ways to get them. Set the return you expect from your savings and see what comes out.
| Buying the whole house | PROPIA | Index fund + renting | |
|---|---|---|---|
| Capital you tie up | €360,000 | €60,000 | €60,000 |
| What you earn a year | ≈ €7,300 (if you manage it yourself) | ≈ €2,708 | ≈ €3,000 (if you sell shares) |
| What you pay for your weeks | €0 | €1,350 (already deducted) | €3,600 |
| Fixed costs out of your pocket | ≈ €9,000 | €0 | €0 |
| Your position at year end | — | ≈ €2,558 | ≈ -€600 |
| Your work | A lot | None | None |
| You can get the money back | Months or more | May take over a year | Usually within a few days |
| Risk if tourism gets regulated | Direct exposure | Shared, but real | No direct exposure |
with a fund at 5%, 2 weeks of use and the same house every year.
Index-fund returns are volatile and their tax treatment depends on the product and your circumstances, but broad funds are generally far more diversified. Property appreciation is not guaranteed; you can exclude it from the simulation. PROPIA concentrates risk in one asset, municipality and use. The table does not claim that PROPIA delivers a higher return: it compares a simulated combination of ownership and use with the estimated cost of holiday rental.
THE QUESTION EVERYONE ASKS
Nobody "gets" August. July and August are the nine weeks that sustain everyone's returns, so they're rented out. Each co-owner has the right to one of those weeks by rotation — it comes round once every three years — and pays its real value, not half price, because otherwise they'd be taking it from the other five. The other two weeks are chosen in the mid season, when the house would often stand empty: that's why they're half price there.
A note on the arithmetic: in the simplified 52-week calendar (364 nights), 140 nights — 18 mid- and low-season weeks plus 2 August weeks — are reserved for co-owners. That leaves 224 nights on the market; the central scenario assumes that 155 are rented, or 69% of the nights offered. The 42% on the home profile is calculated over the 364-night calendar and includes both reserved and unsold nights.
This allocation is a model proposal. The final rules would need to be set out in each home’s shareholders’ agreement and reviewed by a lawyer before signature.
Run the numbers
If you were going on holiday anyway, this combination leaves you €2,250 ahead.
What a guest would pay is not cash you receive: it is what you save by going yourself. The economic advantage of each week is the gap to the co-owner rate: €1,125. What co-owners pay to use the house goes into the common profit and is shared among everyone, so part of it comes back to you; we do not count that here, so as not to inflate the figure. Simulated figures on the Casa Riu central scenario, before tax.
Simulated exampleA PROPIA home
Casa Riu is an example project based on a renovated farmhouse in Ulldecona (Montsià), twenty minutes from the beaches of the Ebro Delta and Alcanar. The simulation assumes valid authorisation for holiday rental, a long rental season and spaces suitable for both guests and co-owners.
185 m² of built space on a 620 m² plot, with three double bedrooms, two terraces, a private pool and a shaded outdoor dining area. The central scenario assumes 155 rental nights a year.
6 investors · no mortgage
Property purchase
€295,000Taxes and purchase costs
€32,000Furniture, fit-out and photography
€15,000Launch reserve
€12,000Legal and administration
€6,000Six contributions of €60,000. No mortgage financing in this example.
Of the €360,000, €65,000 is allocated to taxes, notary fees, furniture, launch costs and reserves rather than the property purchase price. The value of a share should therefore not be assumed to equal the initial contribution from day one. Recovery of capital will depend on income, costs and the eventual sale value and is not guaranteed.
Cleaning between stays is paid by the guest, as is standard in holiday rentals: that's why it doesn't appear as a project cost.
Between replacements (€2,000) and the reserve fund (€1,500), the budget sets aside €3,500 every year. Over eight years that's about €28,000 — roughly the scale of a full furniture and equipment renovation. If a major repair exceeds the fund, co-owners would need to contribute proportionally.
In the central scenario, PROPIA receives about €5,750 a year per home: €2,250 from the 5% variable fee and €3,500 from the fixed management fee.
The central scenario assumes 155 nights rented a year — 42% occupancy — at an average of €291. It does not assume a fully booked house.
| Season | Nights booked | Average price/night | Revenue |
|---|---|---|---|
| High (Jul–Aug) | 55 | €420 | €23,100 |
| Mid (June, Sept., Easter, long weekends) | 60 | €260 | €15,600 |
| Low (rest of the year) | 40 | €160 | €6,400 |
| Total | 155 | €45,100 |
Sensitivity grid: occupancy × average price → gross revenue
| €260/nights | €295/nights | €330/nights | |
|---|---|---|---|
| 36% (131 nights) | €34,100 | €38,700 | €43,300 |
| 42% (153 nights) | €39,800 | €45,100 | €50,500 |
| 48% (175 nights) | €45,500 | €51,600 | €57,800 |
PROPIA charges 5% of rental income and a fixed annual management fee of €3,500 per home.
Get the informationA few PROPIA homes
Ulldecona (Montsià) · 185 m² · 3 bedrooms · private pool
Twenty minutes from the beaches of the Ebro Delta, with two terraces, a shaded outdoor area and 155 rental nights a year.
La Molina · 210 m² · 4 bedrooms · garden and hot tub
A timber home with valley views, fireplace, ski storage and 24 weeks of annual occupancy.
Pals · 160 m² · 3 bedrooms · patio and pool
A restored old-town home with exposed stone, an inner patio and 28 rental weeks a year.
Each home combines a location with proven demand, comfortable spaces for longer stays and a rental operation that works for much of the year.
There is no single future
Simulated estimates before tax. They are not a guarantee of returns.
| Scenario | Revenue | Per investor |
|---|---|---|
| Adverse | €32,000 | ≈ €1,083 |
| Cautious | €38,000 | ≈ €1,833 |
| Central● | €45,000 | ≈ €2,708 |
| Favourable | €52,000 | ≈ €3,583 |
In the central scenario, nominal appreciation of 2% a year would value the property at about €359,600 after ten years. After 5% estimated selling costs, the net share would be roughly €56,930 per investor. Appreciation helps absorb initial costs; it should not be added directly to rental yield.
In the adverse scenario you do not get all your capital back: after ten years you would have recovered about €52,870 of the €60,000 you put in. This is the outcome you must be able to absorb before investing.
The return percentages and 10-year IRR should be read with the assumptions and all four scenarios, not as a standalone headline.
Get the informationA second opinion, with context
Here is a text that summarises the model and your situation. You can review, edit or delete it before sending: you will always see exactly what information it receives.
We've already copied the text to your clipboard: if it doesn't show up pre-loaded, just paste it.
A new tab will open. PROPIA does not receive your conversation or anything you write there.
How we work
And what we rule out: Off-plan new builds, flats in conflictive communities, municipalities with regulation under review, and any price above 8 times revenue.
See the 8 criteria in detail, with an example of a discarded house →
PROPIA charges 5% of rental income plus a fixed management fee of €3,500 a year per house: about €5,750 in total in the central scenario. No fee on your capital, no entry fee, no exit fee, and nothing for buying the house. If the house is not rented, the variable part earns nothing, but the fixed fee covers our minimum structure so the model is a real business once it's replicated across several houses.
Marketing and local operations (20%) will initially be outsourced. If part of this work is later brought in-house, the financial terms for each home will remain those stated in its documentation.
5% × €45,000 ≈ €2,250 + €3,500 ≈ €5,750
Investing through your company? → (in Spanish)
Transparency before promises
Income can vary, the property can lose value and selling a share may not be immediate. There are also regulatory, operational, maintenance and single-asset concentration risks.
Returns, occupancy and appreciation are not assured.
This is designed as a long-term holding, not a daily-liquidity product.
Every opportunity must disclose its budget, risks and terms before any decision.
All figures on this website are before tax. Tax treatment will depend on the final project structure and each investor’s circumstances, so identical gross payouts may produce different net outcomes. We do not provide tax advice or claim any tax advantage: before investing, an adviser should review the documentation and your specific circumstances.
WHAT HAPPENS WHEN YOU DISAGREE
You'll be sharing a house with five strangers for eight to ten years. What matters is not that everything goes well: it's what happens when something doesn't.
The proposed structure includes an annual transfer window, a reference valuation based on an independent appraisal and a 30-day right of first refusal for the other co-owners. If they do not exercise it, the share could be transferred to a third party who accepted the shareholders’ agreement. Without a buyer, the share would not be sold during that window.
This is not liquidity. Exiting can take months or more than a financial year, and the appraisal price may be lower than what you put in.
Planned structure, pending closure with legal advice on each project.
Under the proposed structure, the home would belong to the owning company, not PROPIA. Continuity of shareholder rights and replacement of the manager would depend on the articles, shareholders’ agreement and management contract, all of which require legal review.
BEFORE YOU LEAVE US YOUR EMAIL
If you identify mainly with the second list, PROPIA is unlikely to fit what you are looking for.
With PROPIA, you buy shares in the company that owns the home, in proportion to your contribution. You are a shareholder alongside the other five participants; you do not acquire a direct interest in the property, a right of use or a reservation of weeks.
Co-owner weeks are reserved primarily in the mid and low seasons, when the house often would not be rented out anyway: that's why the rate is half the week's net value. High season is shared by rotation among co-owners and valued at market price, because it's what sustains everyone's returns. And when a co-owner uses the house, their rate goes into the common pot: it takes nothing away from the other five.
In proportion to your share. The model reserves 18 weeks a year for co-owner use, split pro rata: with €60,000 out of €360,000 that comes to 3.
There is an annual transfer window with valuation by independent appraisal, a 30-day right of first refusal for the other co-owners and, if they don't exercise it, a free sale to a third party who accepts the shareholders' agreement. This is an illiquid investment: it can take months, and the price may be lower than what you contributed.
The shareholders' agreement. The management company executes ordinary decisions within the approved budget; selling the house requires a reinforced majority of 4 out of 6 from the fifth year onward, and unanimity before that.
The shareholders’ agreement will need to define the consequences of non-payment, cure periods and any transfer mechanism. This clause will require specific legal review.
Yes. The annual budget sets aside €3,500 between replacements and the reserve fund, which accumulates to about €28,000 over eight years to renovate furniture and equipment. If a major repair exceeds the fund, co-owners would need to contribute proportionally.
All figures on the website are before tax. Tax treatment will depend on the final structure and each investor’s circumstances. We do not provide tax advice: an adviser should review the documentation and your situation before you decide.
That will depend on each project’s legal and tax structure and on your company. It must be confirmed from the final documentation with professional advice.
In the cautious scenario, with €38,000 in revenue, the payout drops to about €1,833 (3.1%); in the adverse scenario, with €32,000, to about €1,083 (1.8%). The €17,500 in fixed costs don't fall; only the 25% variable share does, because marketing, operations and our fee are charged on what is actually billed.
On the Catalan Mediterranean coast and in nearby areas with easy beach access, a long season, a valid and transferable tourist licence and a resale market with recent comparables. Purchase price is decisive: if the numbers don't work right on the coast, we look inland, twenty to thirty minutes from the beach.
The proposal is that you can visit the home and review the full documentation — budget, risks and terms — before making any decision.
A local professional operation handles marketing, guest support, cleaning and coordination. Its 20% of revenue — 10% marketing and 10% operations — is already deducted from every figure you see.
PROPIA charges 5% of rental income plus a fixed management fee of €3,500 a year per house: about €5,750 in total in the central scenario, about €958 per co-owner, and both are visible lines in the cost table, already deducted from every figure you see. No fee on your capital, no entry fee, no exit fee, and nothing for buying the house. The fixed fee exists because the 5% alone doesn't sustain the business once it's replicated across several houses; it's the term for the first houses and stays even if it changes for new houses in the future.
This is a real risk. If holiday rental were restricted, the legally available alternatives would need to be assessed and might include other letting models with lower income. The planning position and holiday-rental authorisation must therefore be verified for each project.
Transfer on death will depend on applicable law, the articles and the shareholders’ agreement, including any right of first refusal. It will require legal review.
Under the proposed structure, the home would belong to the owning company, not PROPIA. Continuity of shareholder rights and replacement of the manager would depend on the articles, shareholders’ agreement and management contract, all of which require legal review.
The information
Receive a confirmation email and tell us if you would like to hear about future PROPIA opportunities.